Financing Your Solar Project
So, you’re ready to harness the abundant Pacific Northwest sun and make the switch to solar energy. It’s a fantastic decision that promises lower electric bills, a smaller carbon footprint, and greater energy independence. As Oregon and Washington’s expert solar installers with over 15 years of experience, we at Sunbridge Solar have helped thousands of homeowners and businesses navigate this exciting transition.
The biggest initial question for most of our clients isn’t about the technology, but about the investment: “What’s the best way to pay for my solar panel system?”
The Critical Question
It’s a critical question. The right financing choice can make your transition to clean energy smooth, affordable, and highly rewarding. The two primary paths are a cash purchase or a solar loan. There’s no single “right” answer—the best option depends entirely on your personal financial situation, your long-term goals, and your comfort level with upfront investments versus monthly payments.
Imagine looking out at the stunning view from Pittock Mansion in Portland or gazing at the iconic Seattle skyline from Kerry Park. Your home, powered by the sun, becomes its own landmark of sustainability and smart financial planning. This guide will provide a clear, comprehensive comparison of paying with cash versus financing with a solar loan to help you make that informed decision.
The Power of Paying with Cash: The Upfront Investment
Paying for your solar panel system in cash is the most straightforward approach. Just as you would buy any other major home improvement, you pay the full cost of the system and installation upfront. For those who have the savings available, this path offers significant financial advantages and the quickest route to maximizing your return on investment (ROI).
The Pros of Paying with Cash
1. Maximum Long-Term Savings & Highest ROI:
This is the number one reason homeowners choose to pay with cash. By avoiding a loan, you eliminate interest payments, which can add thousands of dollars to the total cost of your system over time. Every dollar your solar panels save you on your utility bill is pure profit from day one. Your payback period—the time it takes for the system’s savings to equal its cost—is significantly shorter. Once that threshold is crossed, you’re enjoying free electricity for the remainder of your system’s 25+ year lifespan.
2. Immediate Ownership & Zero Debt:
When you pay cash, you own your solar energy system outright from the moment it’s installed. There are no liens on your property, no monthly loan payments to manage, and no debt associated with your energy production. This clean ownership is a powerful feeling and simplifies your personal finances.
3. Full Access to All Solar Incentives:
As the direct owner of the system, you are eligible for every incentive that is still available — without the complications that come with a lease or PPA. In Washington that means the state’s 100% sales and use tax exemption and net metering; in Oregon it means Energy Trust incentives and net metering. What ownership no longer buys you is the federal residential tax credit: Section 25D ended for systems placed in service after December 31, 2025. Any cash-versus-loan comparison you read that still assumes a 30% federal credit is working from numbers that expired.
You can also take full advantage of state-specific programs like the Oregon Solar + Storage Rebate Program offered through the Energy Trust of Oregon and Washington’s sales tax exemption on solar equipment.
4. Increased Home Value:
Studies have consistently shown that homes with fully owned solar panel systems sell for more than homes without them. A system that is paid in full is a clear asset to potential buyers, not a liability or a financial transfer they have to assume. It’s a powerful selling point, promising lower energy costs from the day they move in.
The Cons of Paying with Cash
1. Significant Upfront Cost:
The most obvious drawback is the high initial capital outlay. A residential solar installation is a major purchase. Dipping into your savings or liquidating other investments to cover this cost isn’t feasible or comfortable for everyone. It could tie up a large amount of liquid cash that might be needed for other opportunities or emergencies.
2. Opportunity Cost:
The money you use for a cash purchase of a solar system could potentially be invested elsewhere. Some may find that investing that same amount in the stock market or other ventures could yield a higher return, even when factoring in the interest paid on a solar loan. This “opportunity cost” is a crucial consideration for the financially savvy homeowner.
3. Slower Path to Going Solar:
If you don’t currently have the full amount saved, you might delay your solar installation for months or even years while you build up the necessary funds. During that waiting period, you’re losing out on potential energy savings and continue to pay high electricity bills to utilities like Portland General Electric.
Financing with a Solar Loan: Go Solar with $0 Down
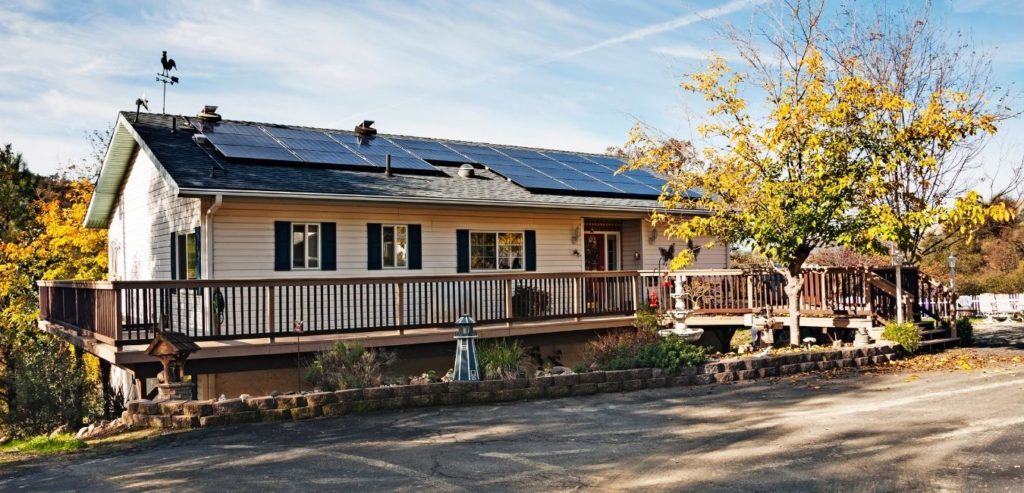
For the vast majority of homeowners, a solar loan is the key that unlocks immediate access to clean energy. Solar loans are specifically designed to finance the purchase of a solar energy system, often with attractive terms and $0 down payment options. This allows you to install your system now and pay for it over time with predictable monthly payments.
The Pros of a Solar Loan
1. No Large Upfront Cost:
This is the most significant advantage of a solar loan. You can go solar without depleting your savings account. Sunbridge Solar partners with trusted local lenders to offer zero-down, low-interest financing options, making solar accessible to a much broader range of homeowners in Oregon and Washington.
2. Immediate Energy Savings:
With a solar loan, you start saving on your electricity bills from the very first month. In many cases, the monthly loan payment is less than your current average utility bill, meaning you are cash-flow positive from day one. You get to enjoy the financial benefits of solar while you pay for the system. It’s like replacing your utility bill with a lower, fixed solar loan payment that eventually disappears.
3. Ownership and Incentive Eligibility:
Unlike a lease or Power Purchase Agreement (PPA), a solar loan means you are still the system owner — and that distinction still matters. As the owner you keep the state and local incentives, the net metering credits, and the increase in home value. You are not handing those to a third party in exchange for a monthly payment. The federal residential credit is gone for everyone as of 2026, so it is no longer the thing that separates owning from leasing. Everything else still is.
4. Fixed, Predictable Payments:
Utility electricity rates are notoriously volatile and have historically increased over time. A solar loan provides a fixed monthly payment that will not go up. This gives you long-term budget certainty and protects you from future rate hikes, whether you’re overlooking the Willamette River or the Cascade Range.
The Cons of a Solar Loan
1. Interest Costs:
Any loan comes with interest. Over the life of the loan, you will pay more for your solar system than you would with a cash purchase. The total cost of the system will be higher due to these financing charges, which in turn extends the payback period.
2. Credit Approval Required:
Securing a solar loan is dependent on your credit score and financial history. While many lenders have programs for a wide range of credit profiles, it is not a guaranteed option for everyone. The loan application and approval process adds an extra step to your solar journey.
3. A Lien on Your Property (Sometimes):
Some solar loans, particularly those structured as home equity loans, are secured loans. This means the lender places a lien on your property until the loan is paid off. However, many solar-specific loans are unsecured, using the solar equipment itself as collateral, which avoids a property lien. It’s essential to understand the terms of the specific loan you are considering.
The 2026 math, with real numbers
Most cash-versus-loan comparisons online still net a 30% federal credit off the system price. That credit ended for homeowners on December 31, 2025, so those comparisons overstate your savings and understate how much financing actually costs. Here is the arithmetic without it.
Take a $25,000 system in Vancouver, WA. These are illustrative figures for showing the method, not a quote — your real number depends on your roof, usage and equipment.
What you pay either way
Washington’s sales and use tax exemption applies regardless of how you pay. At Vancouver’s 8.9% combined rate, that is $2,225 in sales tax never charged on the equipment and installation labor. Paying cash, your total outlay is the $25,000 system price and nothing more.
What financing adds
A solar loan does not change the price of the system. It changes what you ultimately pay for it. At a few representative rates and terms:
| Rate & term | Monthly payment | Total paid | Interest | vs. paying cash |
| 5.99% APR / 12 years | $243.83 | $35,112 | $10,112 | +40% |
| 5.99% APR / 20 years | $178.96 | $42,951 | $17,951 | +72% |
| 6.99% APR / 12 years | $256.96 | $37,003 | $12,003 | +48% |
| 6.99% APR / 20 years | $193.67 | $46,482 | $21,482 | +86% |
| 8.99% APR / 12 years | $284.37 | $40,949 | $15,949 | +64% |
| 8.99% APR / 20 years | $224.77 | $53,945 | $28,945 | +116% |
Two things jump out. Term length matters more than rate. Moving from 12 to 20 years at the same 6.99% drops the monthly payment by $63 but adds $9,479 in interest. And at 20 years, a mid-single-digit rate roughly doubles what the system costs you over its life.
That is not an argument against financing. A $193/month payment against a utility bill you are paying anyway can still make sense, and a system you can actually afford beats one you cannot. It is an argument for going in with the real number rather than one calculated on an incentive that no longer exists.
What this table deliberately leaves out
Your electricity savings. That is the other side of the ledger and it is genuinely household-specific — it depends on your utility, your rate schedule, your usage pattern and how much of your roof gets good sun. A comparison that shows you a payback period without asking about any of that is guessing. We run those numbers against your actual bills before quoting anything.
Figures calculated on a standard amortising loan at the rates shown. Rates and terms vary by lender and credit profile. This is general information, not financial or tax advice — talk to a professional about your own situation.
Making the Right Choice for Your Pacific Northwest Home
| Feature | Paying with Cash | Financing with a Solar Loan |
| Upfront Cost | High initial investment | Low or $0 down |
| Total Lifetime Cost | Lowest possible cost | Higher due to interest |
| Return on Investment | Highest ROI, shortest payback period | Good ROI, longer payback period |
| Monthly Payments | None | Fixed monthly loan payment |
| Ownership | Immediate and outright | Full ownership, loan is a debt |
| Incentive Eligibility | Yes, full and direct access | Yes, full access as system owner |
| Financial Complexity | Simple, one-time transaction | Requires loan application/approval |
| Speed to Install | Can be delayed while saving funds | Immediate installation possible |
Who Should Pay with Cash?
You might be a great candidate for a cash purchase if:
- You have ample savings and can comfortably afford the upfront cost without impacting your financial security.
- Your primary goal is to maximize your total long-term savings and achieve the fastest possible ROI.
- You prefer to live a debt-free lifestyle and want to avoid monthly payments.
Who Should Get a Solar Loan?
A solar loan is likely the best path for you if:
- You want to go solar immediately but don’t have the full cash amount available.
- You want to start saving money on your electricity bills right away, with little to no upfront cost.
- You are comfortable with a fixed monthly payment, especially if it’s lower than your current utility bill.
- You have good credit and can qualify for a low-interest rate.
Frequently Asked Questions
Do I still get a federal tax credit if I take a solar loan in Oregon?
No — and neither does anyone else. The federal residential clean energy credit (Section 25D) was terminated for systems placed in service after December 31, 2025, regardless of how you pay. Ownership still matters for Energy Trust of Oregon incentives, net metering and home value, so the loan-versus-lease question is still worth thinking through. It just is not a question about the federal credit any more.
Ready to Explore Your Options?
Whether you’re leaning towards a cash purchase or a solar loan, the first step is to know your numbers. Sunbridge Solar is here to provide you with a clear, transparent, and customized solar solution. We pride ourselves on our hassle-free, turnkey installations backed by a 10-year craftsmanship warranty and 25-year product warranties.
Let our qualified experts design a system tailored to your home and budget. We’ll walk you through the costs, potential savings, and all available incentives to help you make a confident decision.
Take the next step towards energy independence today!
Fill out our free consultation form online or call us directly at 360-313-7190 for a free, no-obligation estimate.